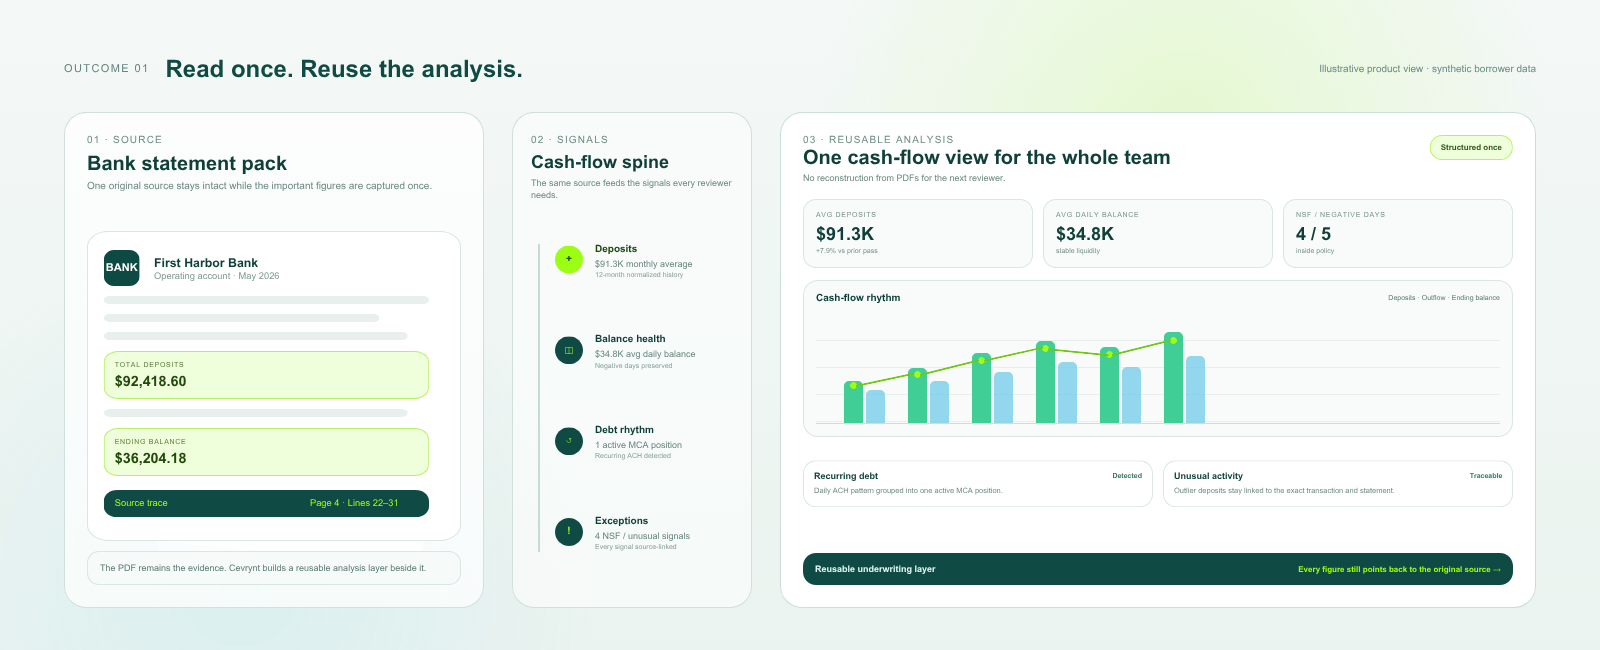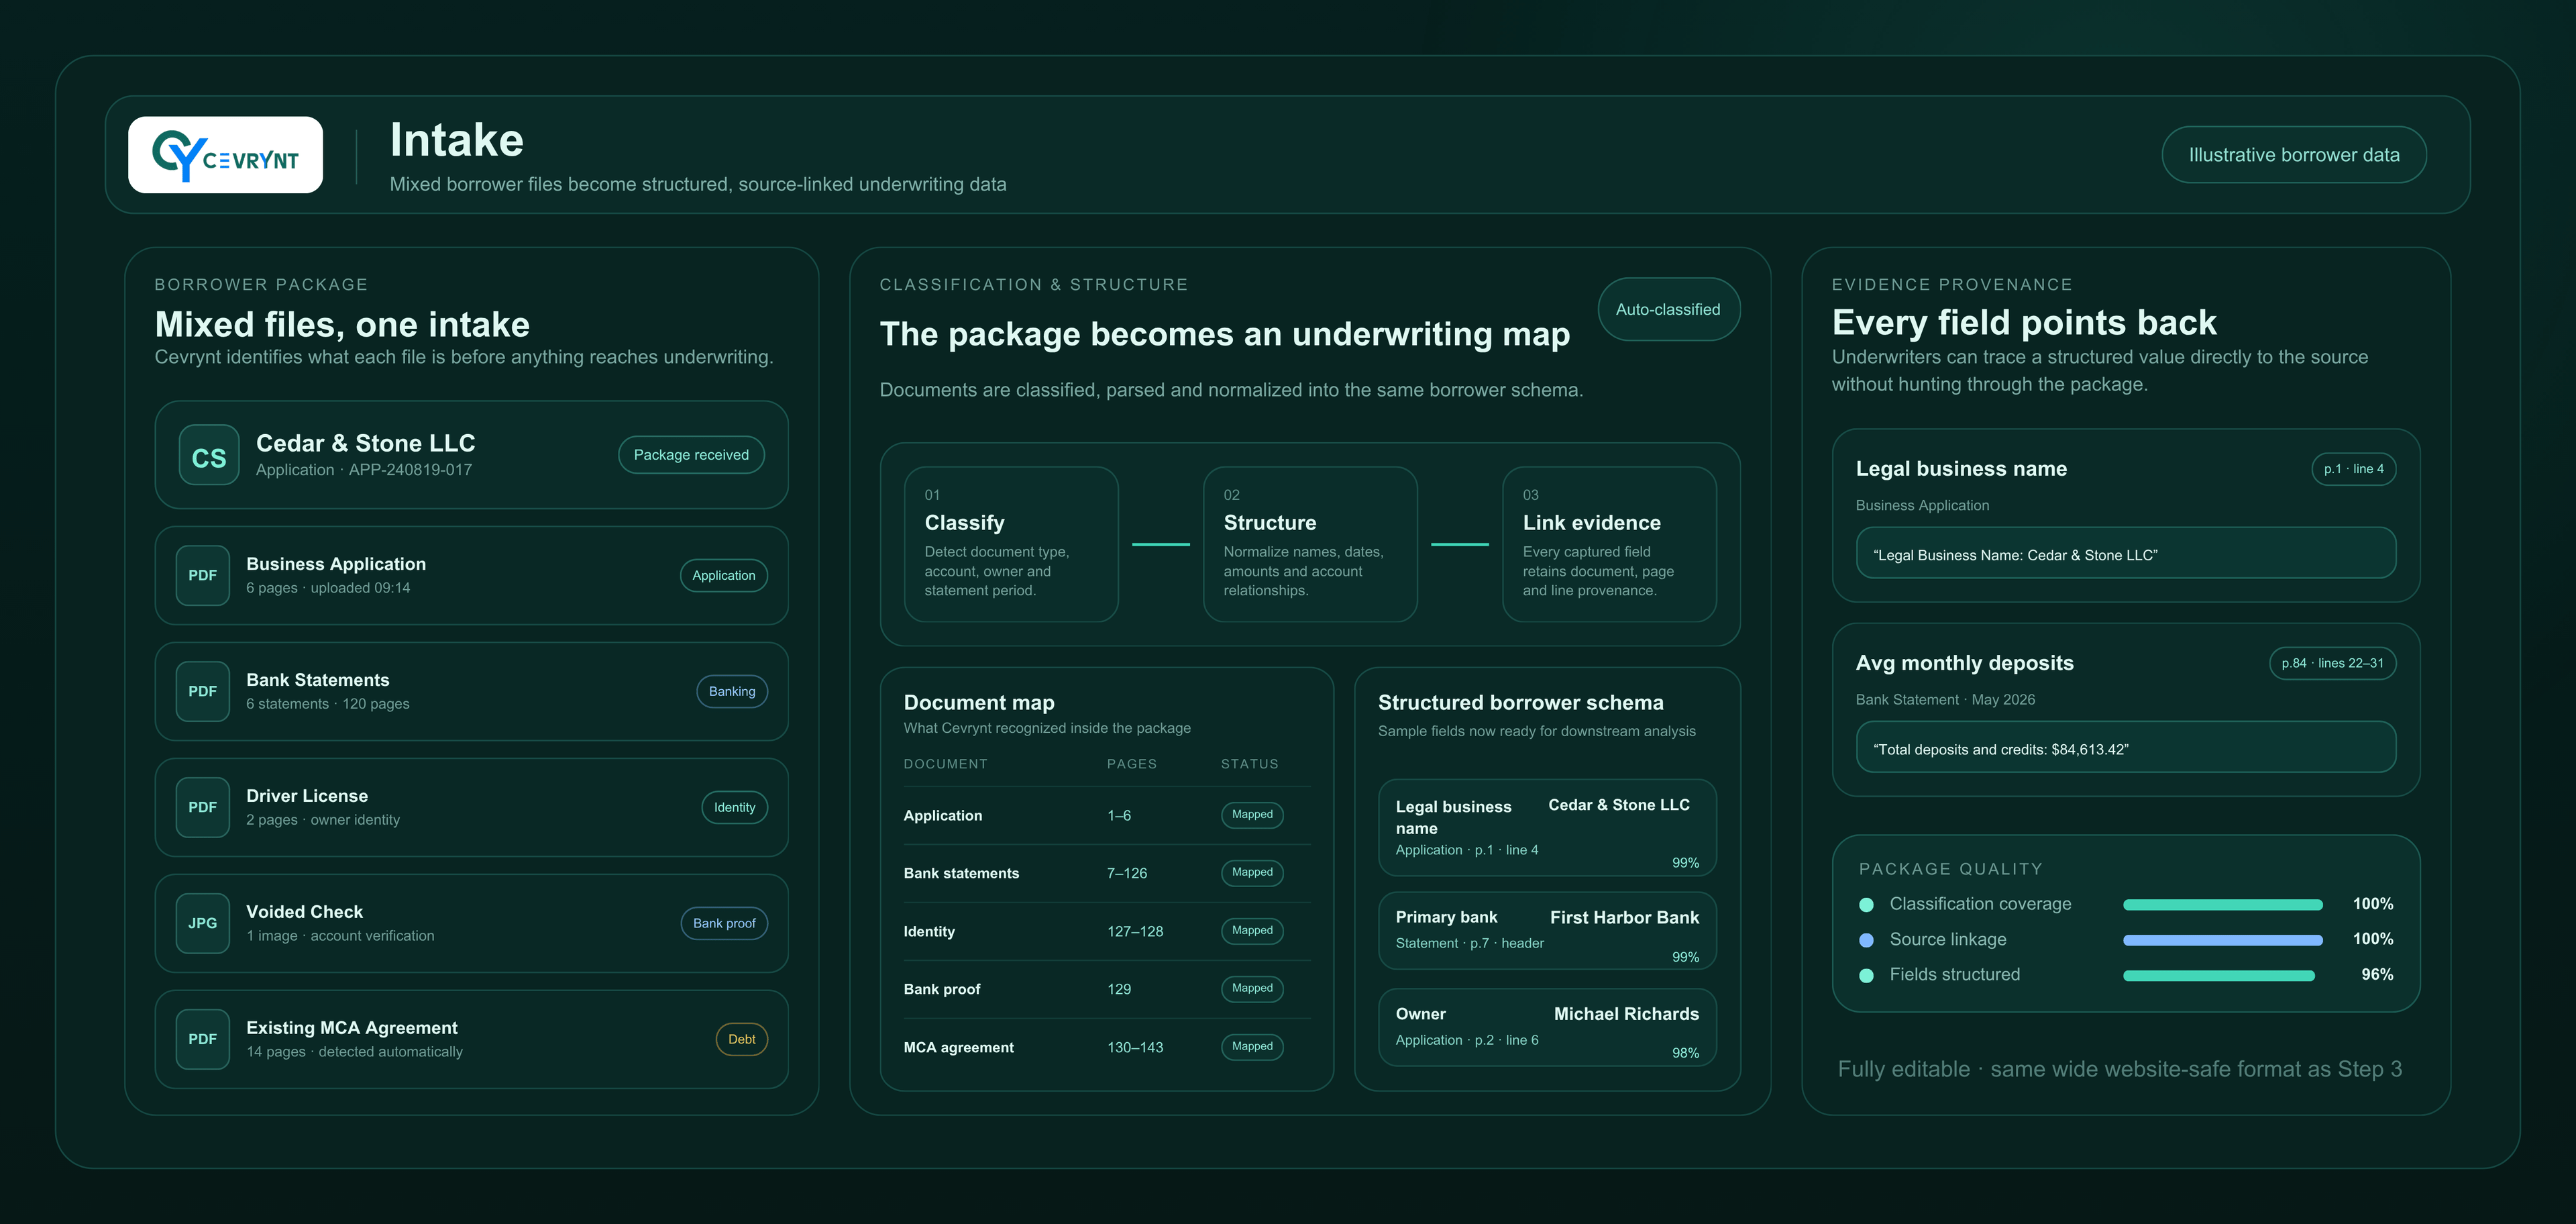
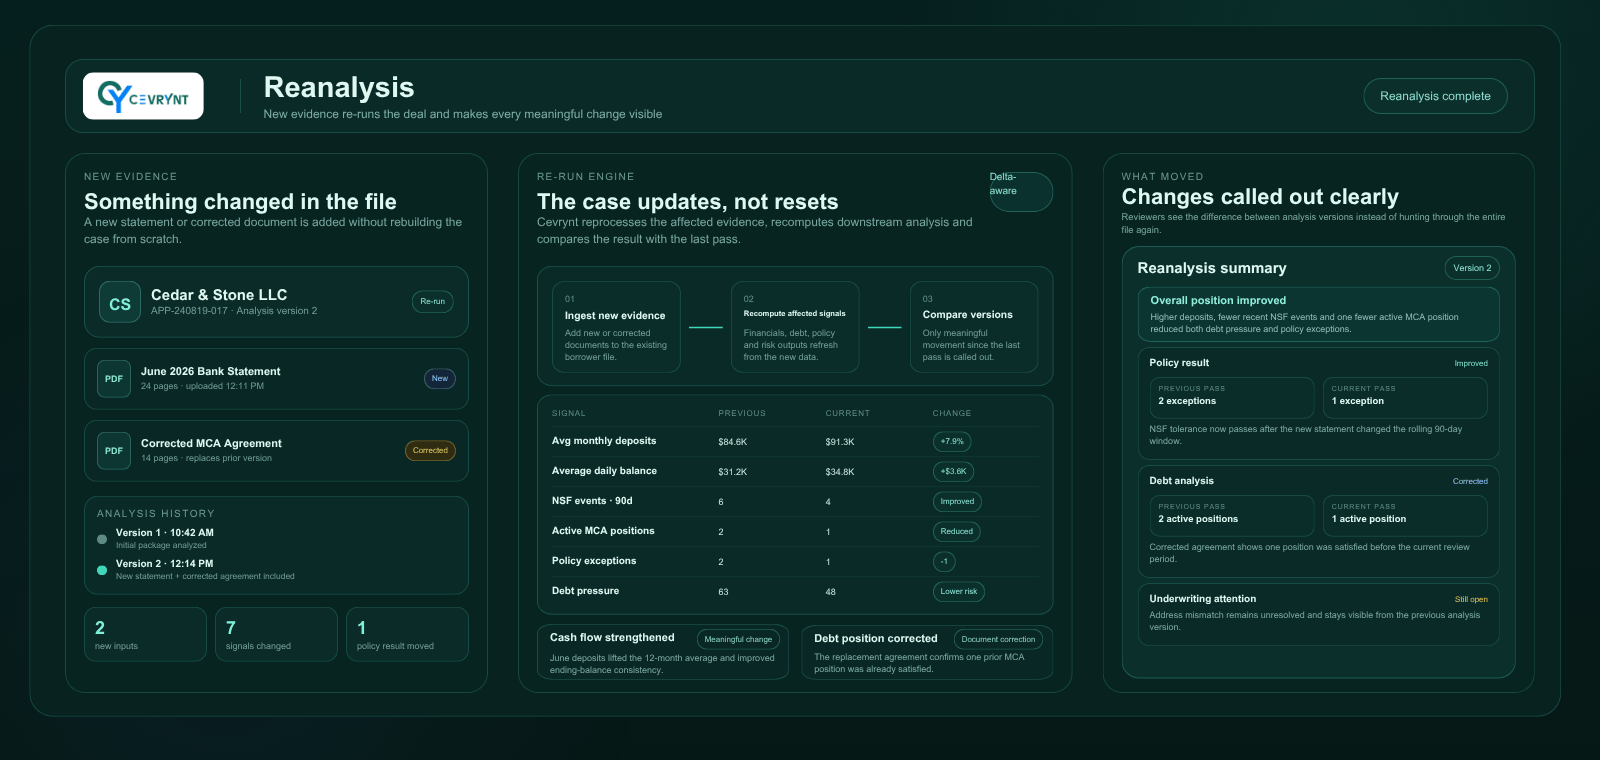
Whatever arrives — applications, statements, IDs, agreements or supporting files — lands against the same deal. Cevrynt keeps the package together before underwriting begins.
Explore capabilityCevrynt · AI underwriting software for MCA & alternative lenders: Underwrite the deal, not the paperwork.
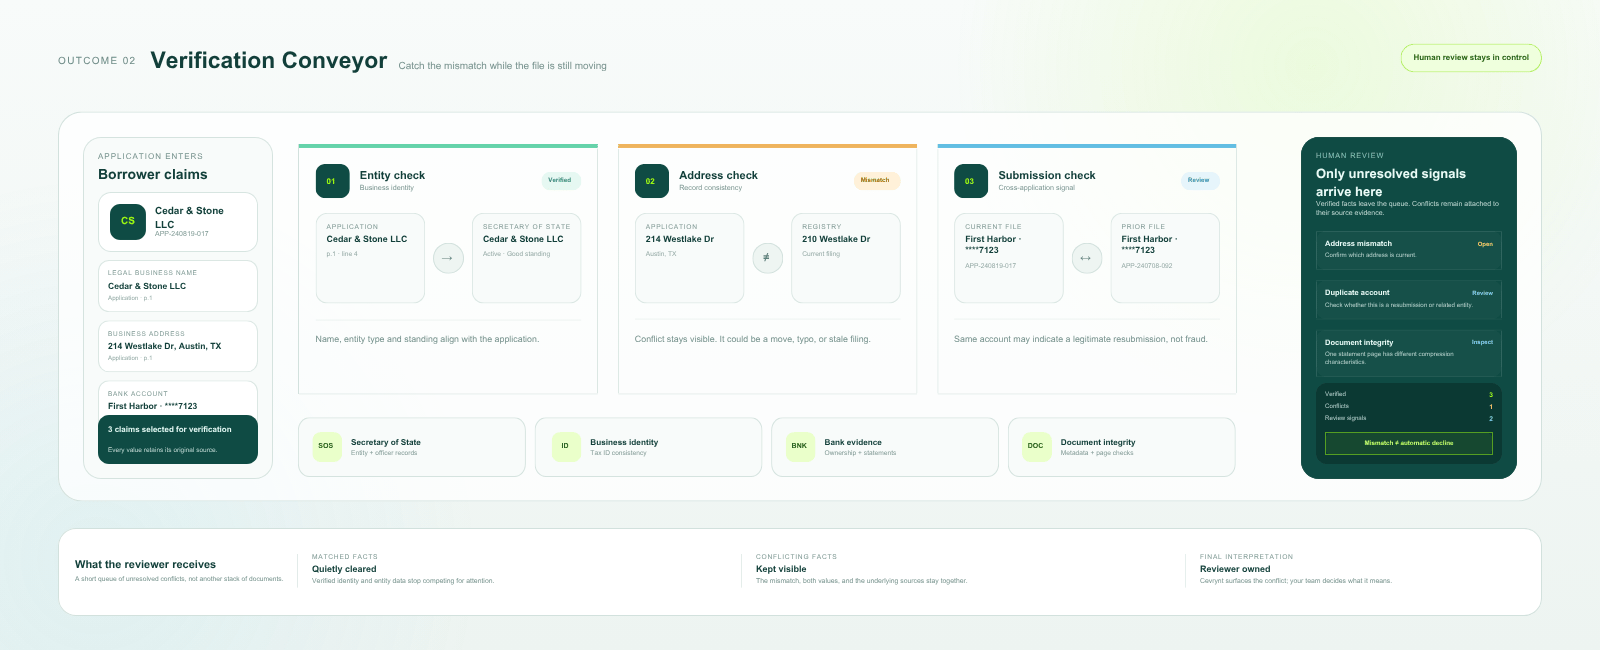
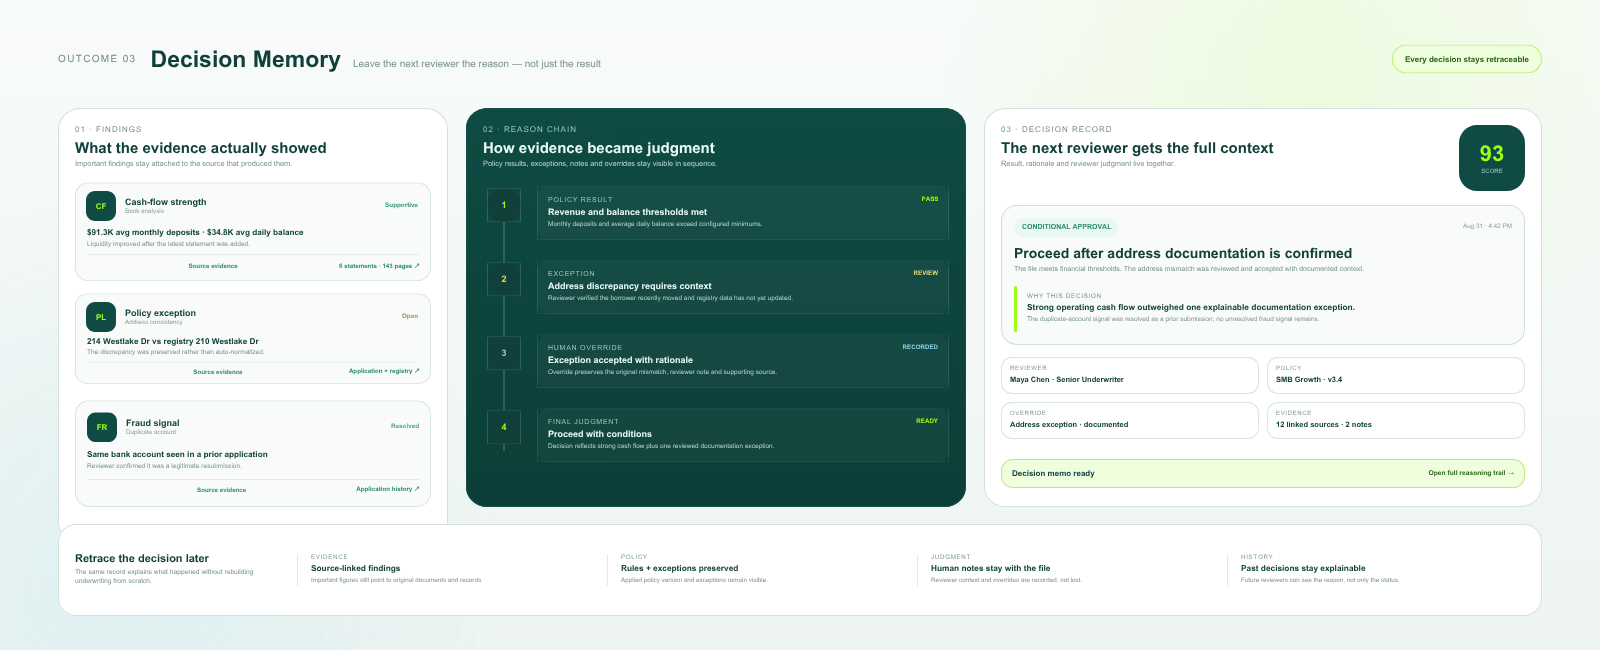
Cevrynt turns borrower documents, bank activity, business checks, debt positions and lender rules into one evidence-linked underwriting view—so your team can review the full story without chasing files across tools.
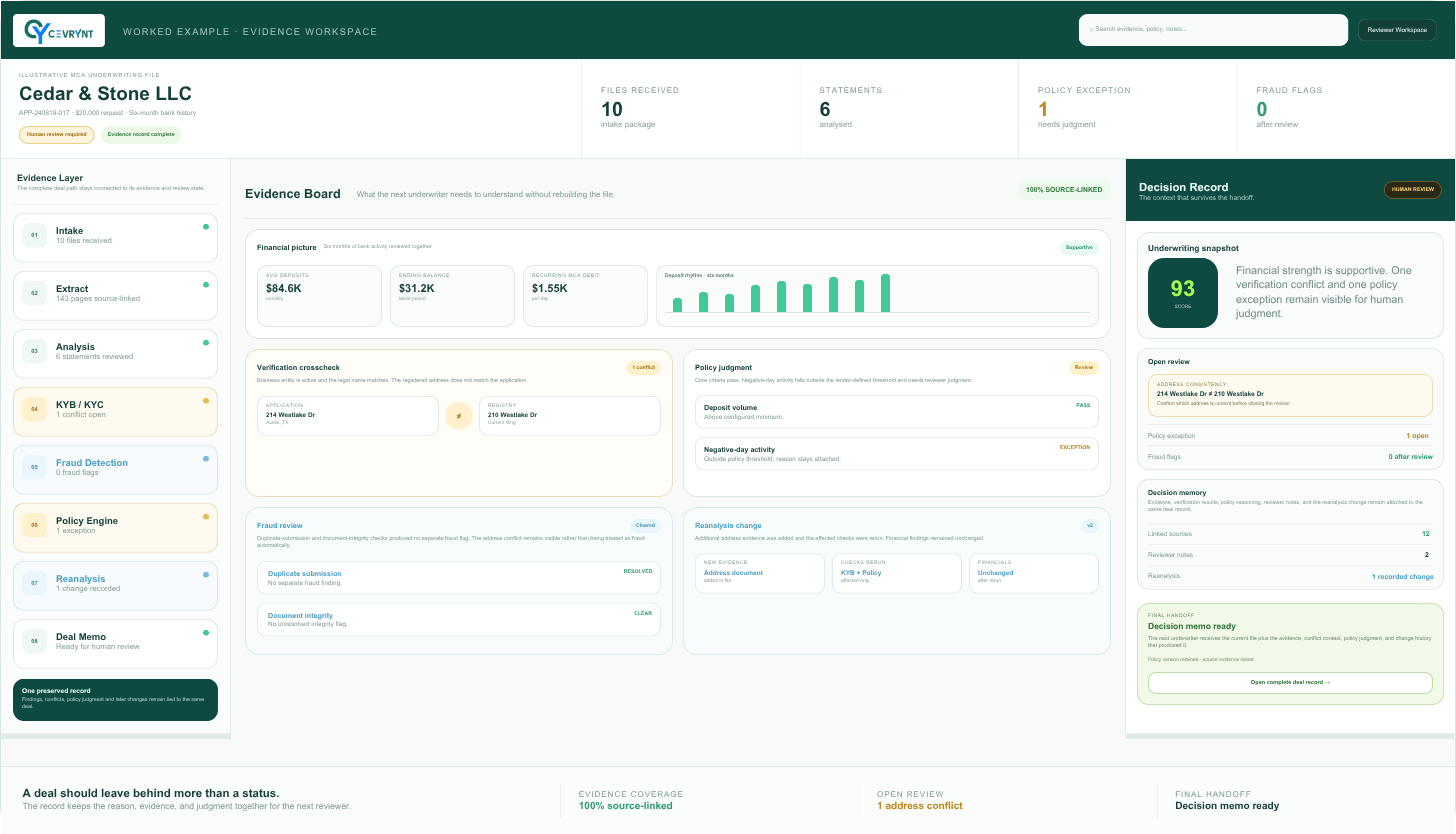
Illustrative example of one deal, Cedar & Stone LLC, moving through Cevrynt:
- Intake: statements, application, owner ID and voided check are classified into one deal.
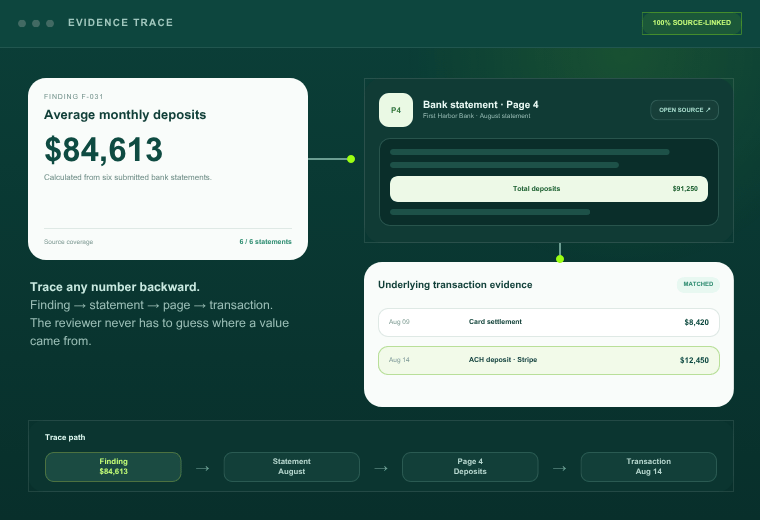
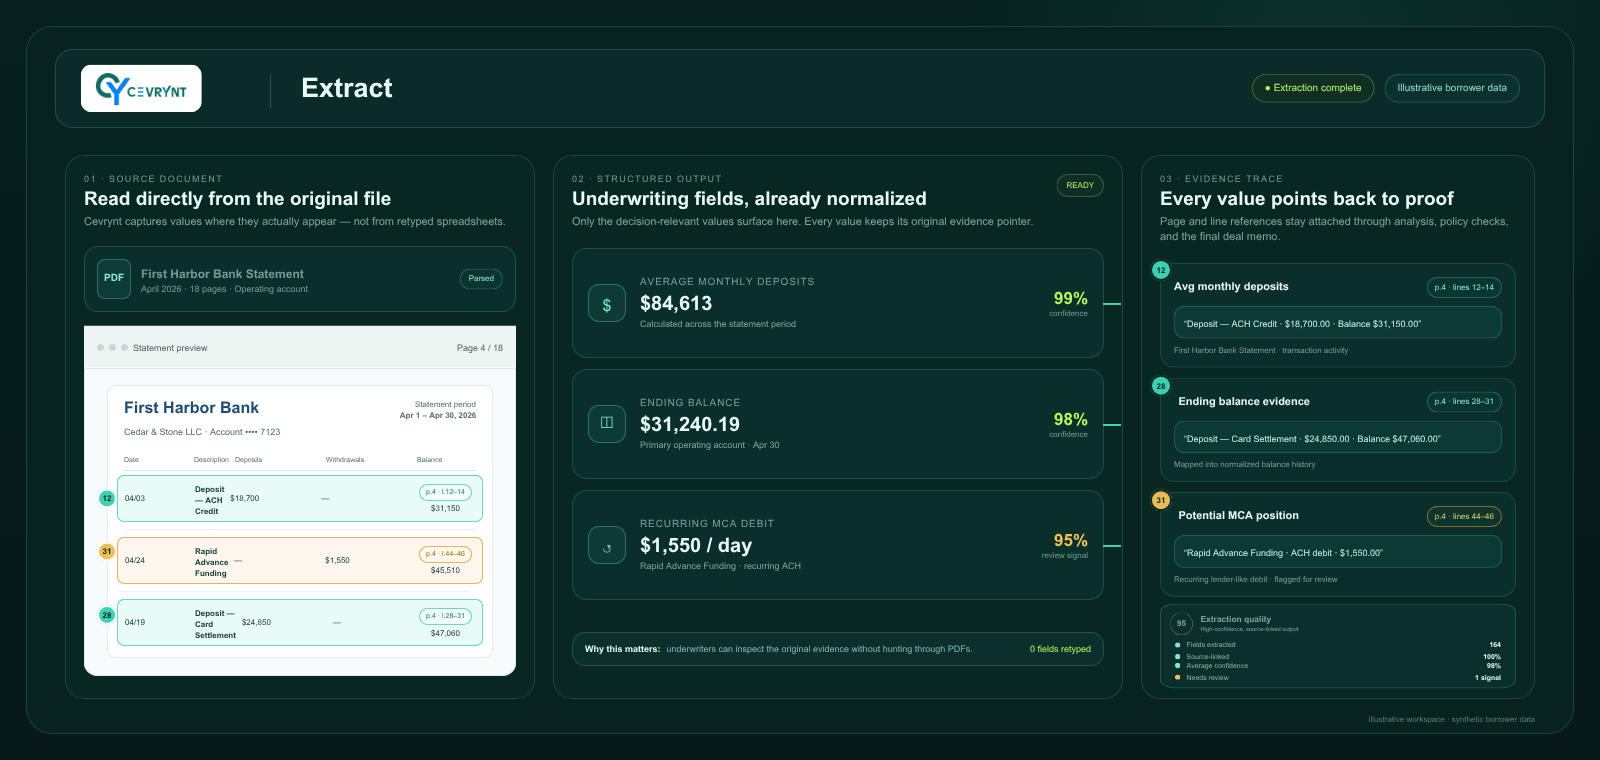
- Extract: values are read from each statement and keep a link to their page and line.
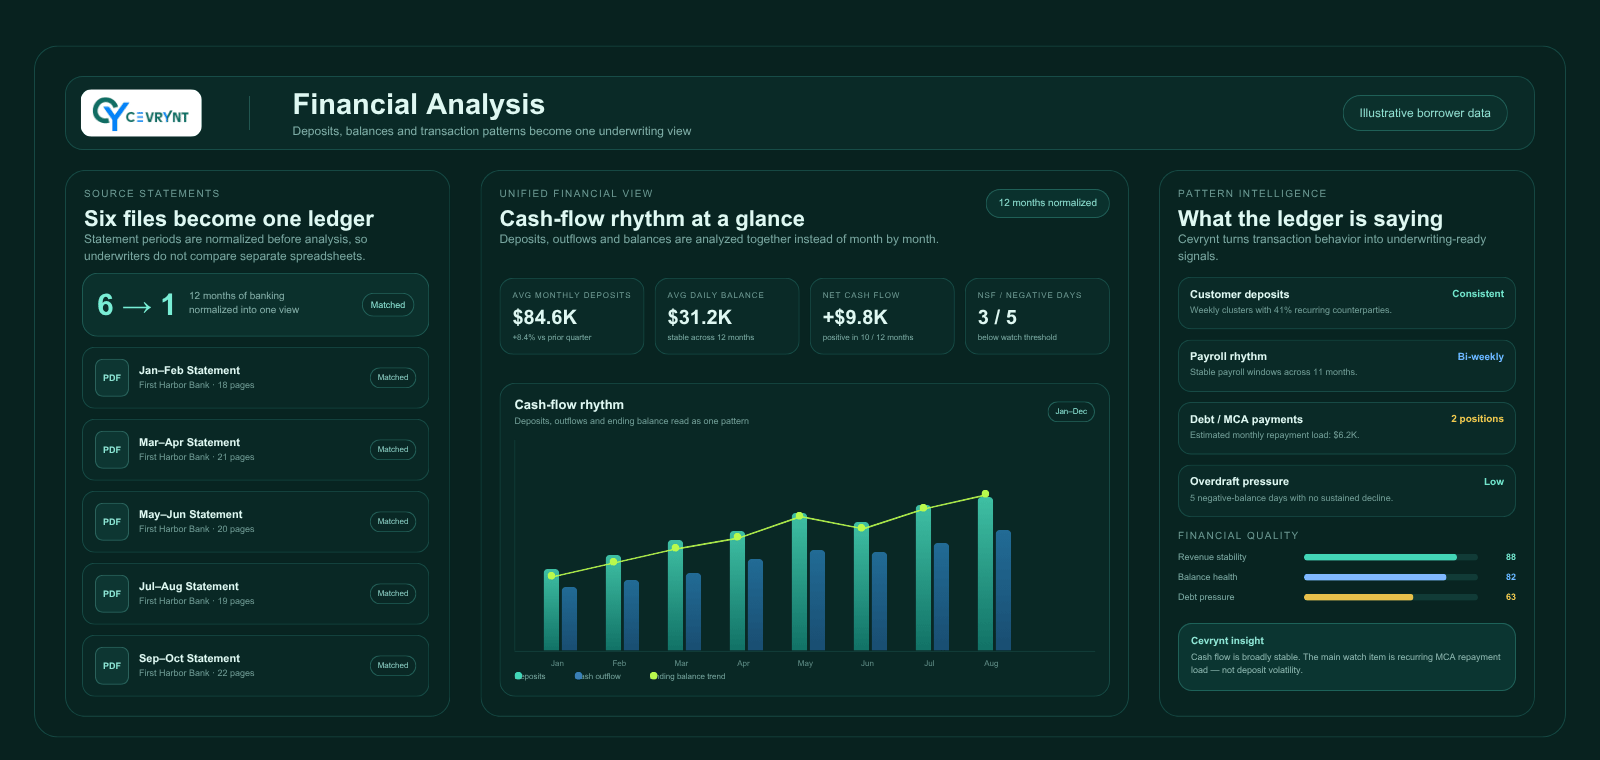
- AI analysis: deposits, daily balance, negative days and existing positions.
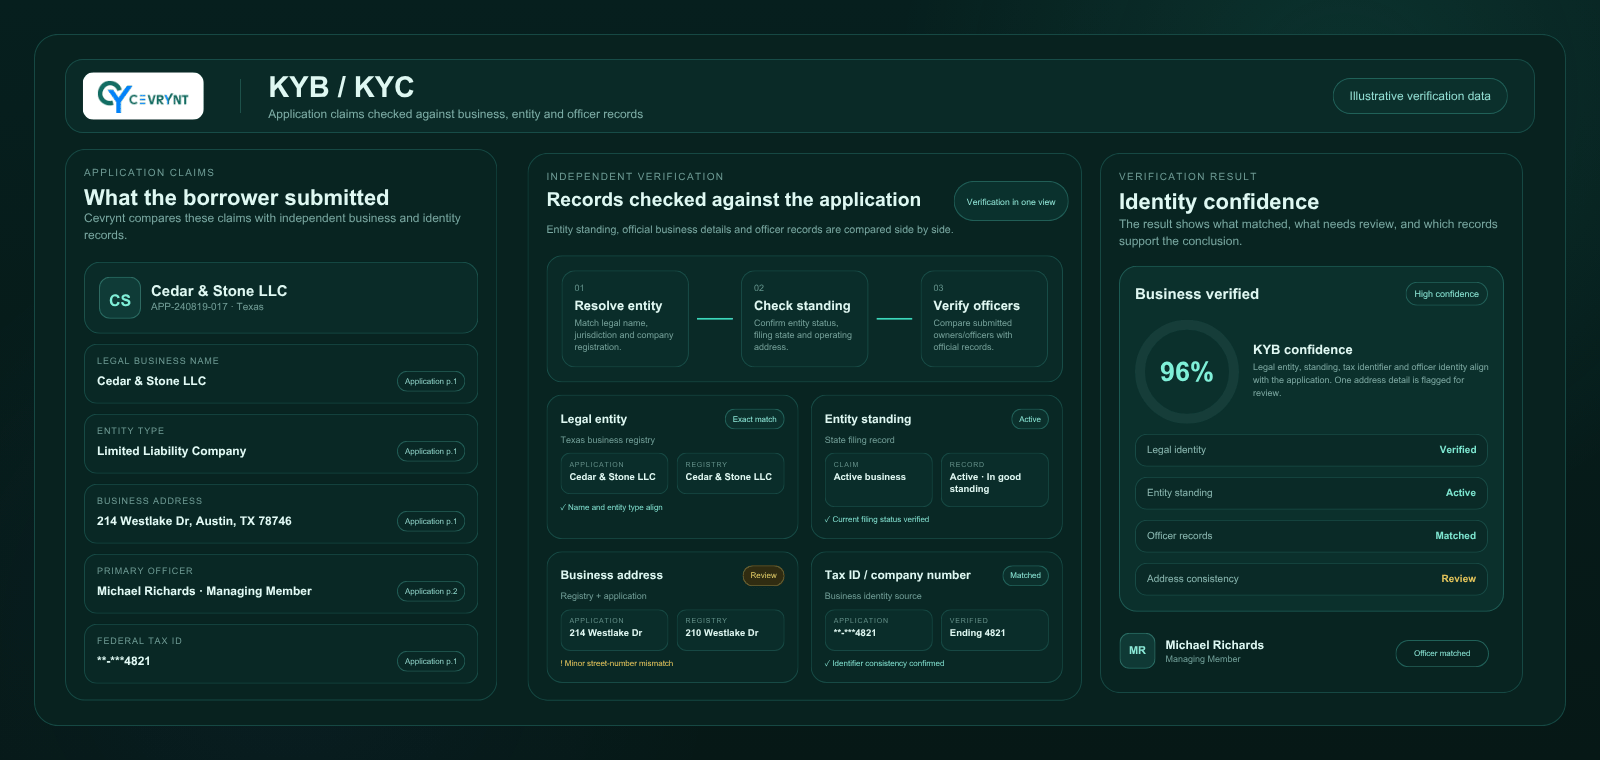
- Business checks: Secretary of State record, owner identity (KYC) and web presence.
- Site checks: the building exists, its business board matches, and the neighbourhood is commercial rather than residential.
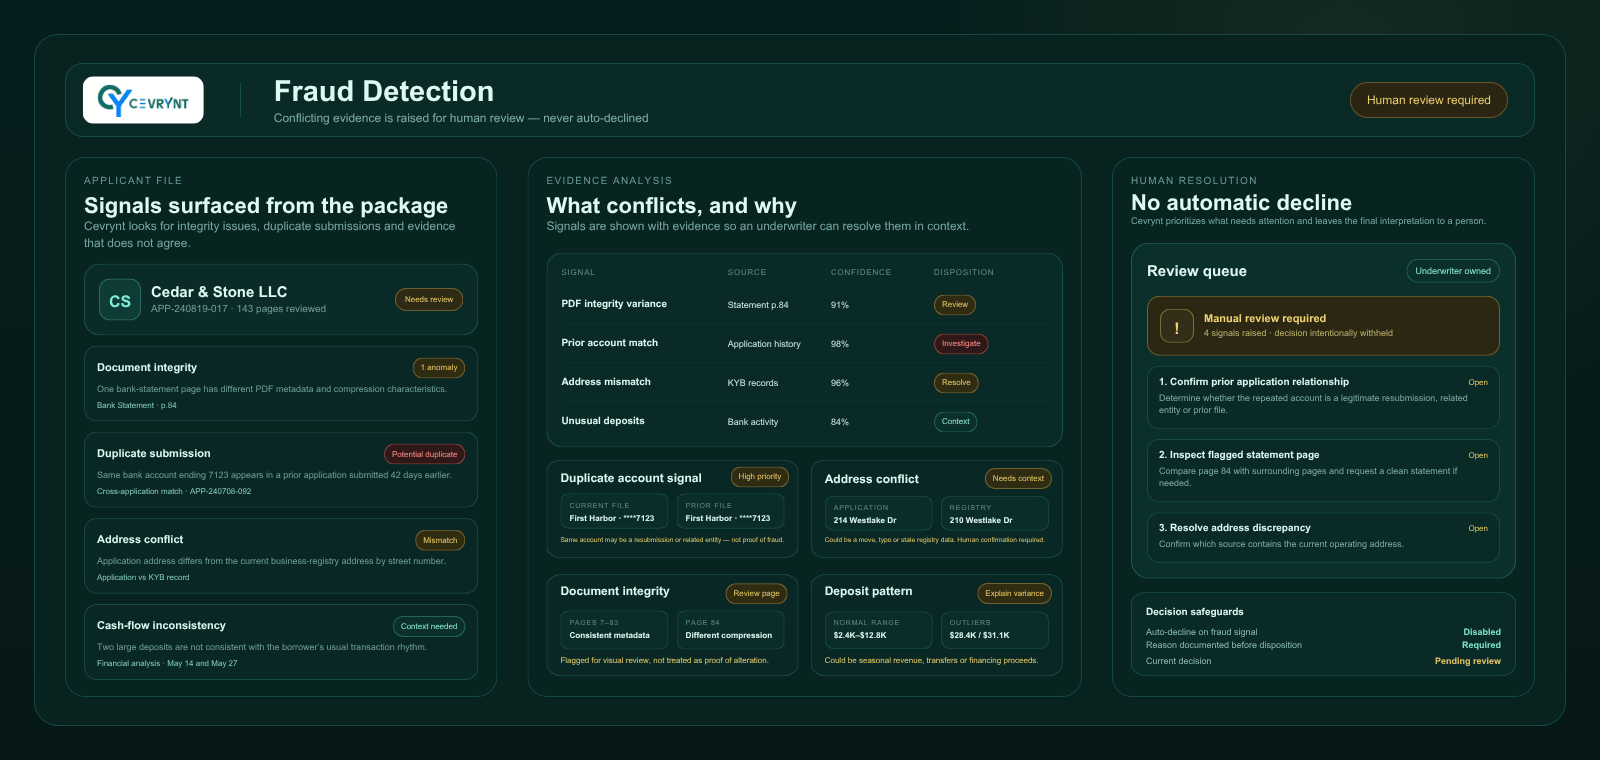
- Fraud detection: an edited statement page is flagged for a reviewer.
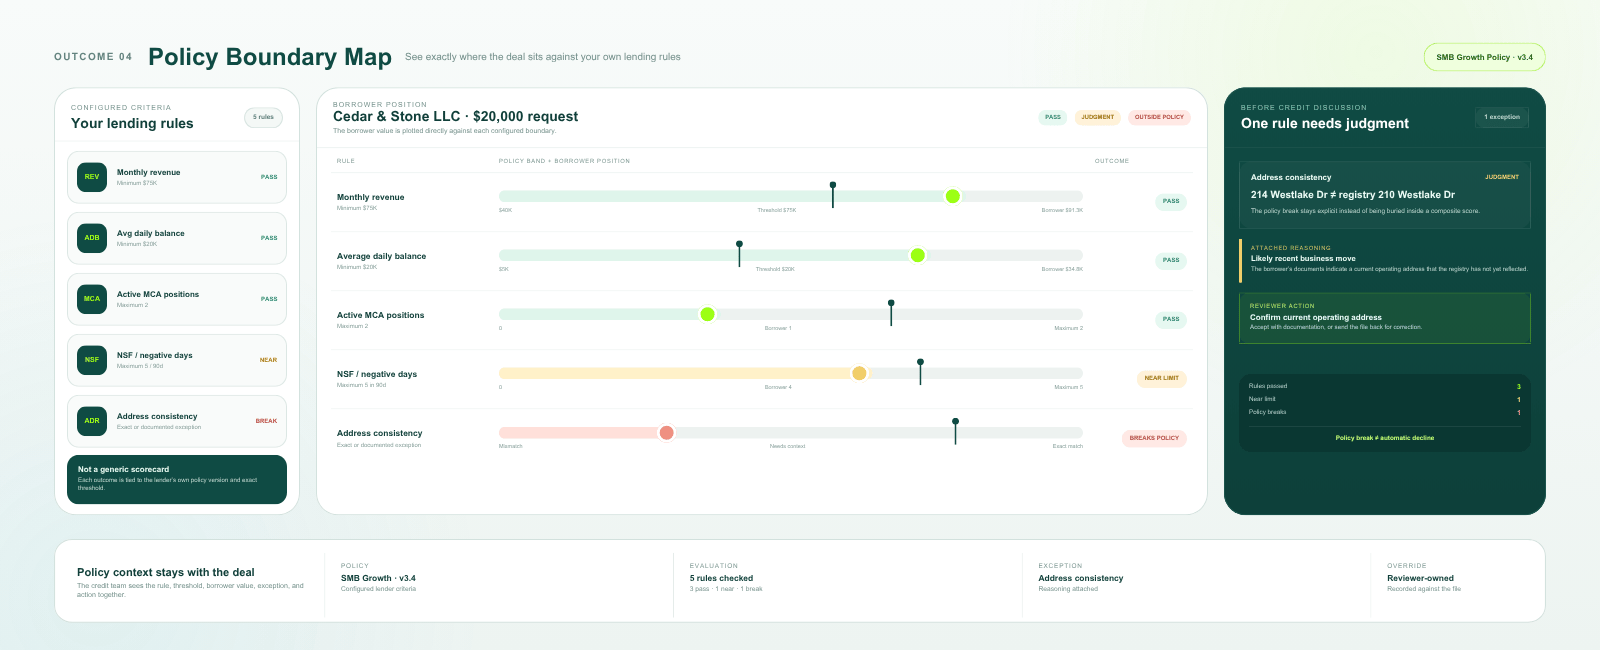
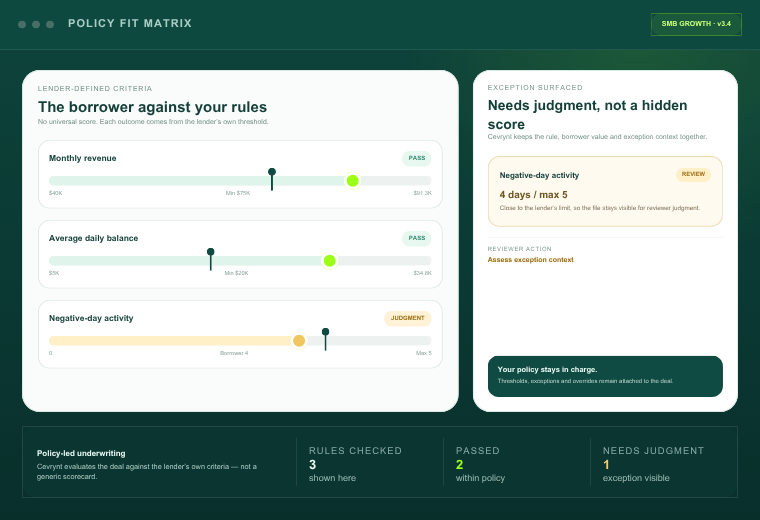
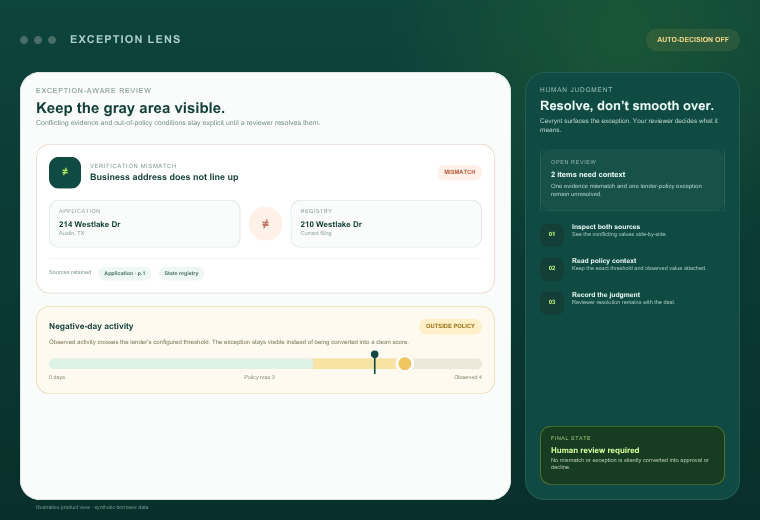
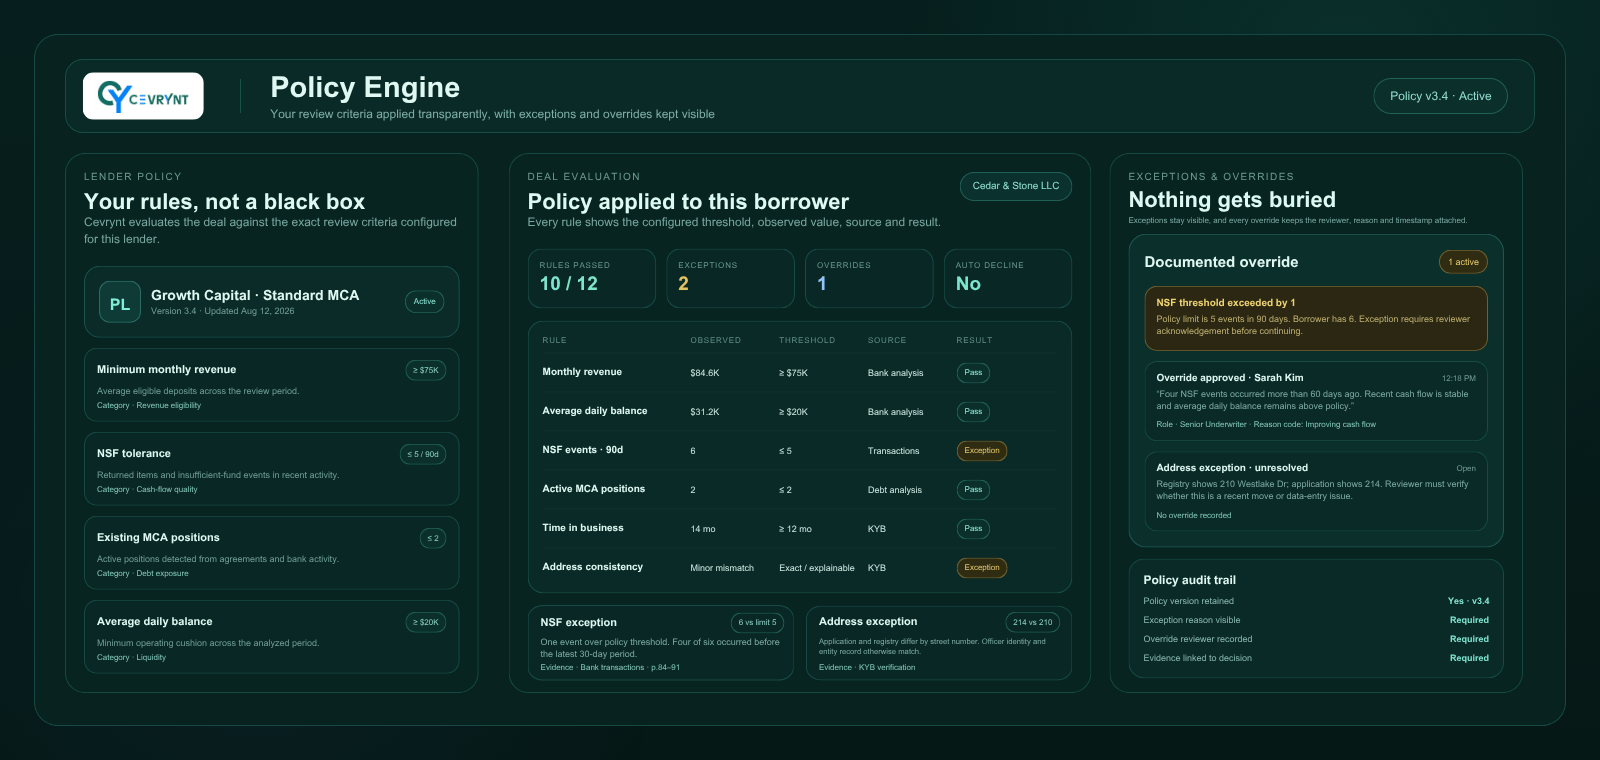
- Policy checklist (optional): the lender's rules are applied and one exception stays visible.
- Re-analysis: a corrected page arrives and only the affected figures re-run.
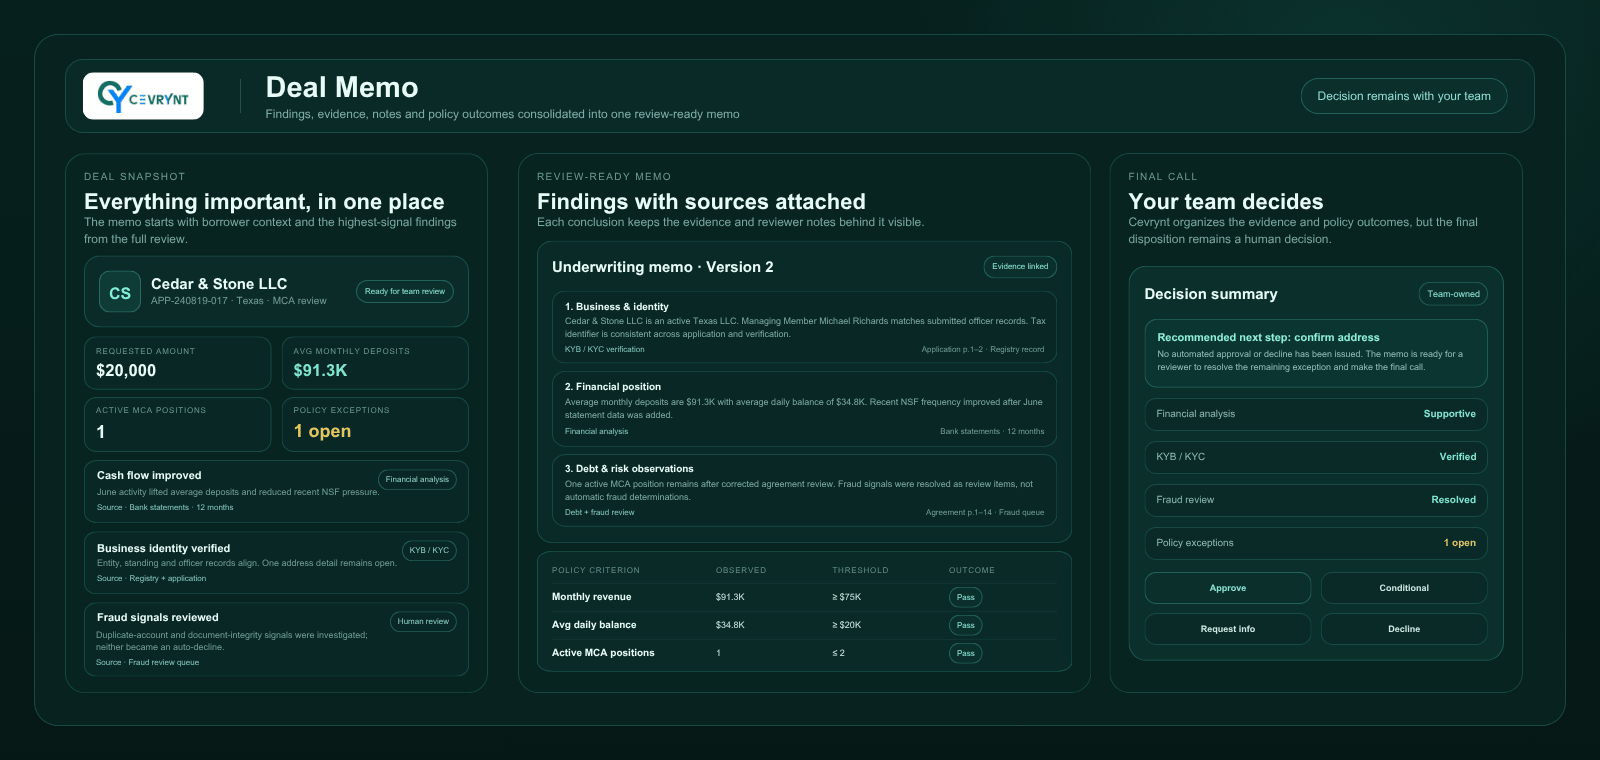
- Memo: findings with evidence, an amount range from the lender's policy, and the underwriter's logged decision.
Cedar & Stone LLC · one file, start to decision
01Intake
Classified asBank statements · Jan–Jun ×6
Classified asBusiness application
Classified asOwner ID
Classified asVoided check
9 files · classified · 1 deal
02Extract
Deposit · ACH$18,420.00
Recurring debit · Northbay Cap.$1,240 weekly
Overdraft fee1 this month
Every value keeps a link to the page and line it came from.
03AI analysis
Average monthly deposits$84,210
Negative days3 · all in April
Existing positions2 funders · weekly debits
AI noteApril dip follows lower card sales
04SOS · KYC · Web
Secretary of State · DelawareActive · formed 2016
Owner identity (KYC)Matches registered member
Web presenceSite and listings agree
05Address · Street view
Building existsTwo-storey commercial unit
Business boardSignage reads Cedar & Stone
NeighbourhoodCommercial strip · not residential
Shared addressNo other recent applicant
06Fraud detection
Font on page 4Differs on one line
PDF metadataEdited after issue
Duplicate submissionNone found
Flag raised · needs a reviewerCevrynt shows why. Your team makes the call.
07Policy checklistOptional
Rules met5 of 6
Exception · kept visibleIntegrity flag still open
Runs when your team has a policy loaded. Nothing is scored behind your back.
08Re-analysis
- Apr 08 deposit
- $17,450
- $7,450
- Avg monthly deposits
- $85,880
- $84,210
- Balance math · p.4
- Breaks
- Reconciles
- Integrity rule
- Exception
- Met
Version 1 and the reviewer’s note stay in the audit history.
09Memo · decision
Amount range your policy supports$40,000 – $55,000
$0From your rules · not an offer
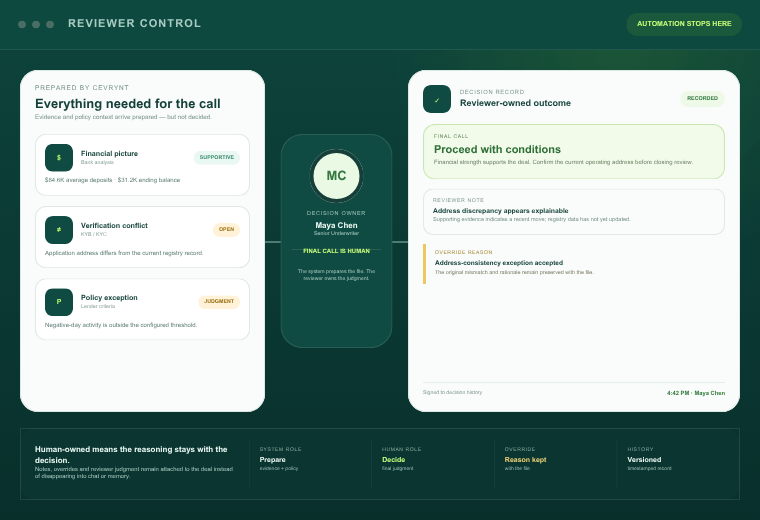
UWUnderwriterFinal decision
Approved with conditions · $45,000Logged with evidence and note
13
Before you ask
The questions underwriting teams ask before they put real files through Cevrynt.
Short answers to the questions that usually come before a pilot. Security, data handling, deployment, and deeper integration questions are covered in the full FAQ.
Does Cevrynt make credit decisions or replace underwriters?
No. Cevrynt prepares the underwriting work — structuring documents, analysing bank activity, checking business and fraud signals, applying lender-defined policy, and keeping the evidence together. Your team reviews the exceptions and makes the final approval, decline, counter, pricing, or structuring decision.
Can Cevrynt work with our existing underwriting policy?
Yes. Cevrynt is designed around the rules your team already uses, including thresholds, conditions, document requirements, and exception paths. It shows where a deal fits policy, where it does not, and why. If an underwriter overrides the result, that judgment stays recorded with the file.
Do we need an LOS or API integration before we can test Cevrynt?
No. A pilot can start with a bounded workflow and representative historical files, without turning the first evaluation into an integration project. If the results justify moving forward, the production workflow and integrations can be scoped around the systems your team already uses.
How do you measure whether Cevrynt is accurate enough for our workflow?
We do not treat approval rate as an accuracy metric — approval depends on your policy and risk appetite. In a pilot, we compare Cevrynt against files your underwriters already know and measure things that can actually be checked: extracted values, financial calculations, source links, conflicts surfaced, policy results, false or missed flags, and how often a reviewer needs to correct the output.
Is the Cevrynt × SHOPLINE partnership a live integration?
Not as a universally available, plug-and-play integration today. Cevrynt and SHOPLINE have a development and referral partnership around e-commerce merchant underwriting. Any production data flow depends on the specific implementation, merchant authorization, permitted data access, and lender use case. The partnership should not be read as automatic data sharing, automatic underwriting, or guaranteed funding eligibility.